
This article contains affiliate links. If you book through them we may earn a commission at no extra cost to you.
These are the two cards that define the premium segment, and the comparison is genuinely close. The Platinum Card from American Express sits at roughly $895 a year; the Chase Sapphire Reserve at roughly $795. Both hand back most of that in credits if you use them. Both open lounge doors. Both transfer points to airline and hotel partners.
The difference is philosophical, and once you see it the choice usually makes itself.
The One-Sentence Version
Amex Platinum is an access card. It buys you into places — lounges, hotel programmes, elite status, reservations — and pays you back in credits that only work if your spending matches the categories Amex chose.
Chase Sapphire Reserve is a spending card. It earns more on the travel and dining you were going to buy anyway, returns value in a broader and less prescriptive form, and gets out of your way.
Lounge Access
This is Amex’s clearest win and the reason many people hold the card at all.
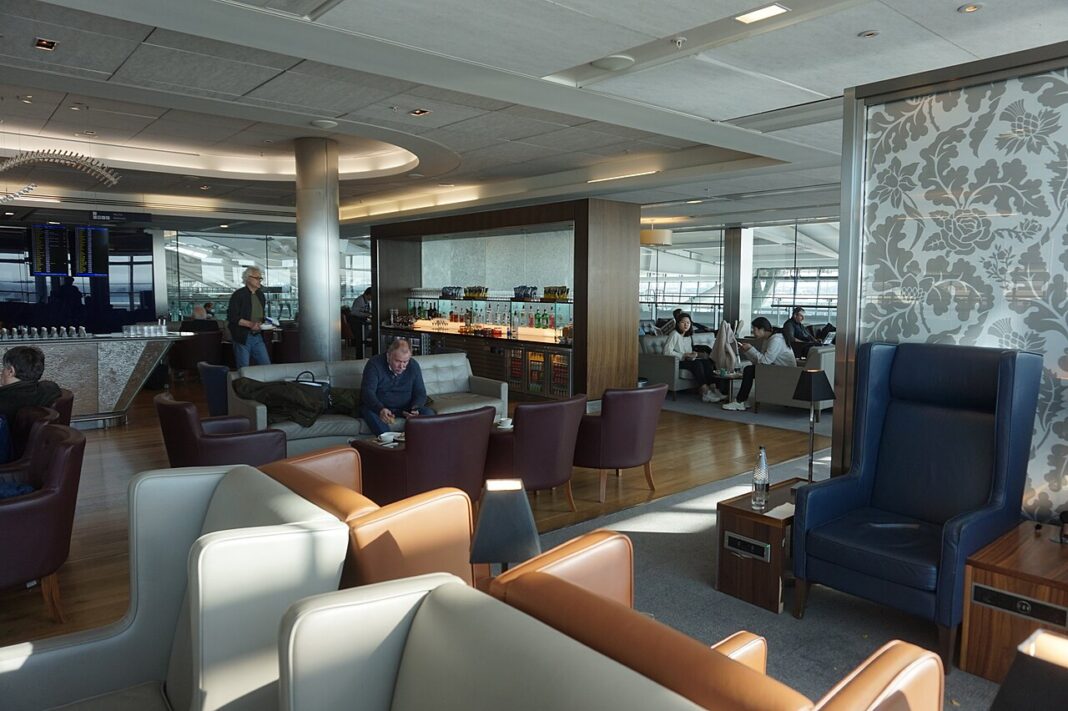
Platinum delivers the Global Lounge Collection: Centurion Lounges, Delta Sky Clubs when flying Delta, Priority Pass select lounges, Escape and Plaza Premium lounges, and a handful of partner networks. It is the broadest lounge portfolio attached to any consumer card, though Centurion Lounges have become notoriously crowded at peak hours and Delta Sky Club access now carries annual visit limits for Platinum holders.
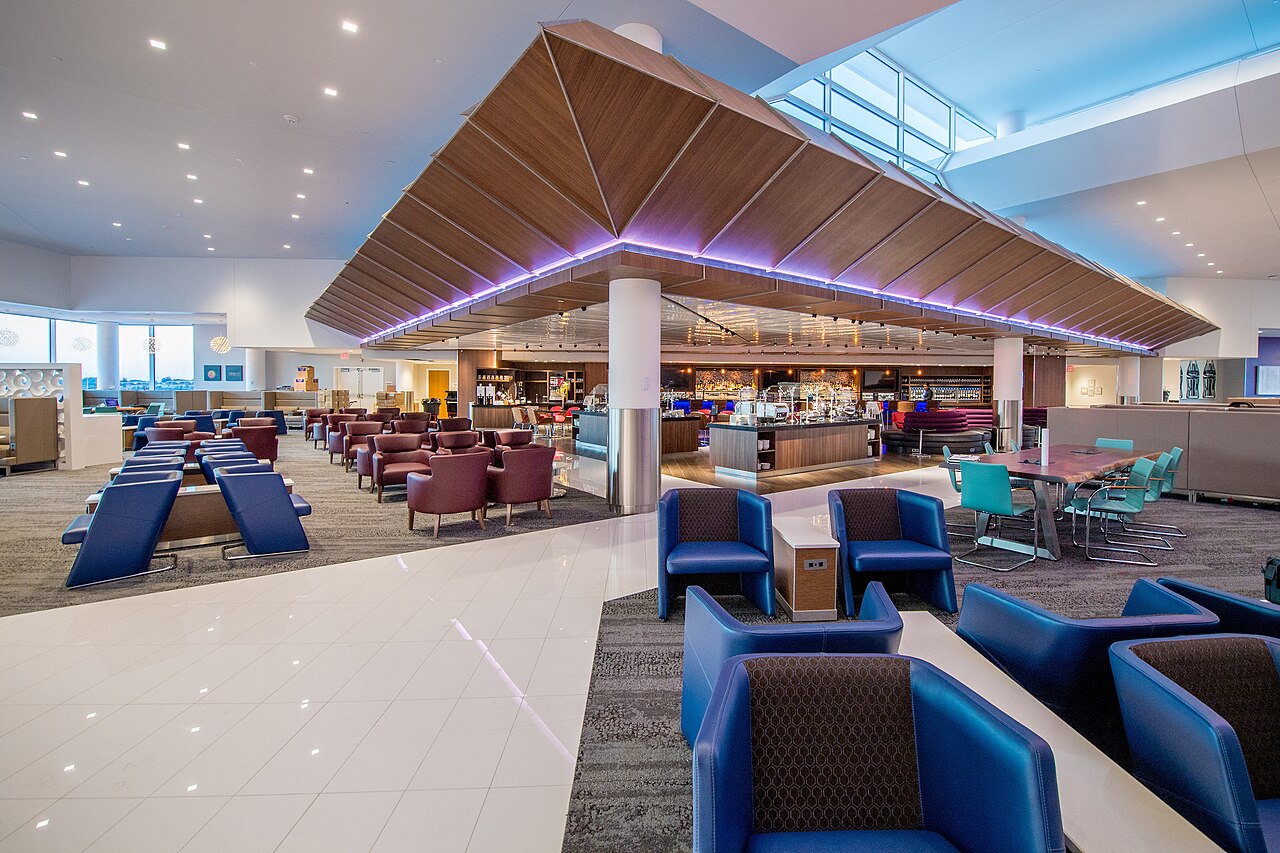
Sapphire Reserve offers Priority Pass Select plus the growing network of Chase Sapphire Lounges, which are newer, generally less crowded and — in the properties opened so far — better designed than the Centurion equivalent. The network is far smaller, but it is expanding quickly; a new Sapphire Lounge is coming to Sea-Tac.
Verdict: Amex on breadth, Chase on the quality of its own rooms. If you fly Delta, Amex is not close.
Hotel Benefits
Amex wins decisively here, and it is not a matter of taste.
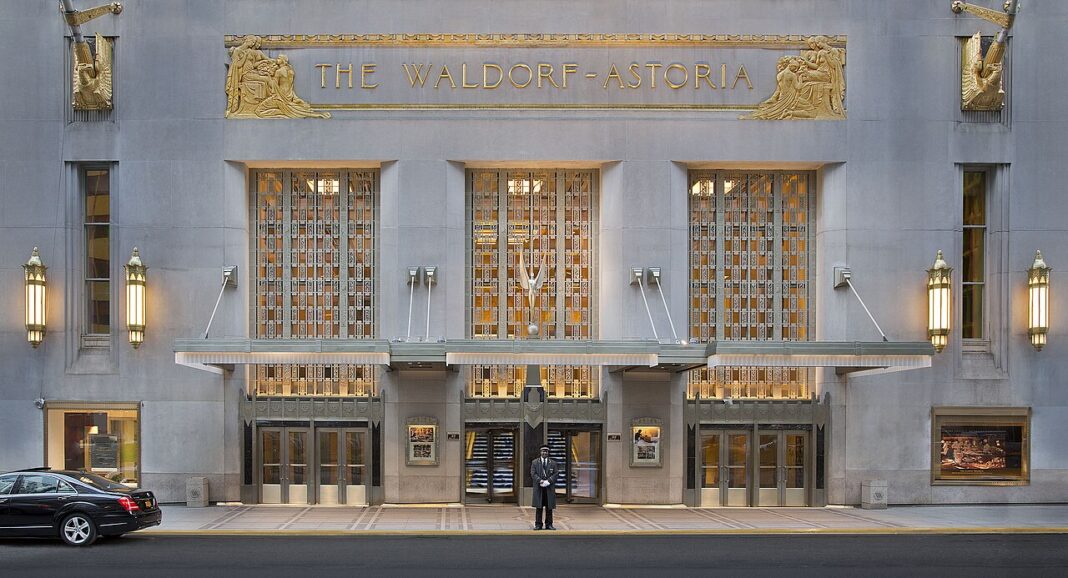
Platinum unlocks Fine Hotels + Resorts, which layers breakfast for two, a room upgrade, guaranteed late checkout and a roughly $100 property credit onto stays at luxury hotels — often at the same rate you would pay direct. It also confers Marriott Bonvoy Gold and Hilton Honors Gold status outright.
Sapphire Reserve has The Edit, Chase’s curated luxury hotel collection, which delivers a comparable package of breakfast and a property credit. The concept is the same; the portfolio is smaller and less established.
Verdict: Amex, on portfolio depth. If you stay in five-star hotels more than a few times a year, FHR alone can justify the annual fee.
Earning and Redeeming Points
Sapphire Reserve wins on earning. It pays elevated multiples on travel and dining booked anywhere, which describes most of what a frequent traveller actually spends money on. Amex Platinum earns strongly on airfare booked directly or through Amex Travel, and unremarkably on nearly everything else — restaurants included, which is a real gap.
On redemption, both transfer to strong airline and hotel partners at 1:1. Chase’s roster is anchored by Hyatt, whose award chart remains the most valuable use of transferable points in the industry. Amex has a deeper airline partner list including ANA, Singapore and Virgin Atlantic.
Both also let you spend points through their own booking portals, and in both cases that is usually the worst thing you can do with them. We cover why in our guide to using the Amex Travel portal.
Verdict: Chase on earning, roughly even on redemption, with the edge to Chase if you value Hyatt.
The Credits: Read These Carefully
Both cards return most of the annual fee in credits, but the two approaches differ sharply.
Amex credits are numerous, narrow and category-locked — airline incidentals, specific streaming and retail partners, hotel bookings made through Amex Travel, rideshare, and several that reset semi-annually. Used fully, they exceed the fee. Ignored, they are worth nothing, and many cardholders ignore most of them.
Chase’s headline credit is a broad annual travel credit that applies automatically against almost any travel purchase, plus dining and lifestyle credits that are narrower but still relatively easy to trigger.
Verdict: Chase, for anyone who will not manage a spreadsheet. Amex, for anyone who will.
Who Should Hold Which
Choose Amex Platinum if you stay in luxury hotels regularly, fly Delta, want the widest lounge network, value having Bonvoy and Hilton Gold handed to you, and will actually use category-specific credits.
Choose Chase Sapphire Reserve if you spend heavily on travel and restaurants, want a credit that applies without thought, value World of Hyatt transfers, or simply prefer a card that does not require active management to break even.
Hold both if your travel spending is high enough that the combined roughly $1,700 in annual fees is comfortably outweighed — which happens sooner than people expect once FHR stays and both sets of credits are in play.
The Bottom Line
Amex Platinum is the better card for luxury hotel travel and lounge breadth. Chase Sapphire Reserve is the better card for everyday travel spending and for people who want value without vigilance. Neither is objectively superior; they are optimised for different travellers.
For the wider field — including Capital One Venture X and Citi Strata Elite — see our comparison of the best luxury travel credit cards.
Annual fees, credits and benefits on both cards change regularly. Confirm current terms with the issuer before applying. This is general information, not personalised financial advice.
Image credits: Heathrow Terminal 5 club lounge — photo by Ian S, CC BY-SA 2.0 via Wikimedia Commons. Delta Sky Club — photo by Chris Rank / Rank Studios for Delta News Hub, CC BY 2.0 via Wikimedia Commons.